

MoodWallet: Money Management
by Jomo Labs
4.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.3
- Price
- Free
- Download
- 10.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
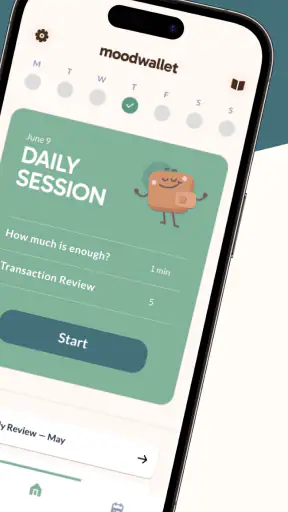
 Analysis by Getfullapps
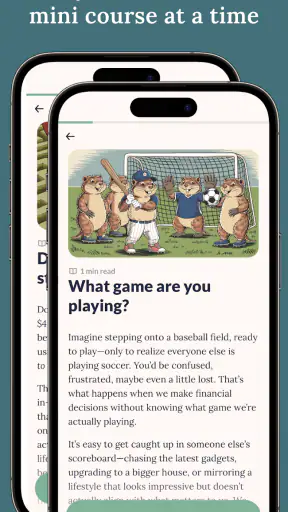
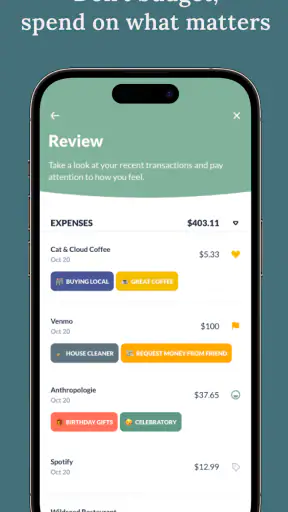
I went into MoodWallet: Money Management expecting another finance app that would ask me to build a detailed budget and then make me feel guilty when real life got in the way. Its approach is different. The focus is on the emotional side of spending: noticing how a purchase fits into my mood and helping me make calmer choices without turning every transaction into a spreadsheet exercise.
That makes it appealing during the first few days. The app is free to start, belongs to the finance category, and comes from Jomo Labs. It is rated for Everyone, so its presentation feels approachable rather than aimed only at experienced personal-finance users. The store summary promises less stress and better spending without traditional budgeting, and that is a useful way to understand its personality: this is more of a spending-awareness companion than a full accounting system.
My main question after the initial curiosity was whether the idea could survive ordinary life. Finance apps often feel impressive during setup and then become another notification to dismiss. MoodWallet has a better chance than a conventional budget tracker for people who dislike rigid categories, but its lasting value depends on whether you are willing to pause and reflect honestly. It does not remove the need for financial judgment; it tries to make that judgment easier to practice.
What MoodWallet feels like in the first week
The first-week appeal comes from the lower pressure. A conventional budgeting app usually asks me to define income, recurring bills, spending limits, and categories before it becomes useful. MoodWallet’s concept feels more personal and less administrative. Instead of beginning with a financial plan that may already be out of date, I can use it as a prompt to ask why I am spending and how the decision feels.
That distinction matters for someone whose problem is not a lack of arithmetic. I may already know that frequent takeaway meals, impulse shopping, or small digital purchases add up. The harder part is recognizing the moment when I am tired, bored, stressed, or looking for a quick reward. An emotion-centered tool can be useful precisely because it places attention on that moment rather than waiting until the end of the month to show me a disappointing total.
I would recommend starting with a small, repeatable routine instead of trying to record every financial decision immediately. For example, I might use the app around discretionary purchases for a week and pay attention to patterns. The goal is not to label every expense perfectly. The useful question is whether the pause changes my next choice. If it does, the app is doing something a basic transaction list cannot do.
A realistic example is a late evening after work. I open a food-delivery app because I am exhausted, not because I have planned a meal. With MoodWallet in my routine, I can stop long enough to identify the feeling behind the purchase. I might still order, and that is important: the app should not turn every treat into a failure. But I may choose a cheaper option, delay the order, or recognize that this is a recurring stress response worth addressing elsewhere.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
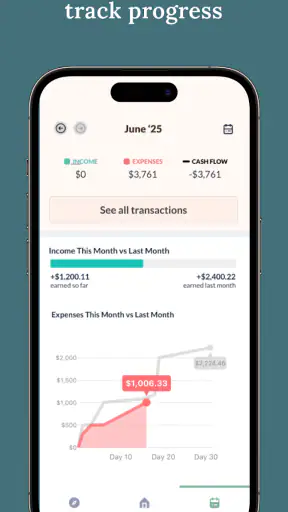
This is also where the app’s limits become clear. Mood awareness is not the same as financial visibility. If I need to know exactly how much remains for rent, compare bills across months, reconcile accounts, or prepare for a major purchase, I would still want a more traditional finance tool or a simple spreadsheet beside it. MoodWallet makes the decision-making moment more visible; it is not a replacement for every form of money management.
The app’s free price lowers the risk of trying it, although optional in-app purchases range from six dollars and ninety-nine cents to eighty-nine dollars and ninety-nine cents per item. That is a wide range, so I would pay attention to what is available before treating it as a completely cost-free long-term system. The free entry point is helpful for testing the habit, while the paid options make it worth deciding whether the deeper experience genuinely supports my routine.
Who gets the most from the concept
MoodWallet makes the most sense for someone who already knows the basics of personal finance but struggles with impulse spending or emotional purchases. It may also suit a person who has abandoned strict budgeting systems because they felt too demanding. The app’s softer approach can be a bridge between “I should control my money” and actually noticing the decisions that cause trouble.
It is less suitable for users who want automatic account management, detailed forecasting, debt payoff calculations, investment tracking, or formal reports. I would also hesitate to recommend it as the only tool for a household managing shared finances. Emotional reflection can improve individual choices, but it does not replace clear agreements, accurate records, and practical planning between partners or family members.
Whether the value survives beyond the novelty
The first month is where I would judge the app more seriously. A new money app can feel helpful simply because it makes me think about money more often. That effect may fade once the interface becomes familiar. MoodWallet earns a lasting place only if its prompts lead to a repeatable change: fewer automatic purchases, more deliberate treats, or a clearer understanding of the situations that make me overspend.
For month-to-month use, I would treat it as a reflection layer rather than a complete financial command center. I can use it before or after selected purchases, then review the emotional patterns that keep appearing. The most valuable insight may not be a dramatic saving. It could be discovering that I spend more when I am procrastinating, that convenience purchases cluster around certain routines, or that some “necessary” expenses are actually attempts to solve fatigue with money.
One useful workflow is to choose a single category of discretionary spending for a month. I might focus on impulse online orders instead of trying to examine groceries, transport, entertainment, and bills at once. That creates a clearer experiment. I can ask whether the pause changes frequency, timing, or amount. Concentrating on one behavior also reduces the risk that the app becomes a daily obligation I resent.
Another practical approach is to connect the app with an existing weekly money check-in. I could review my bank balance or regular budgeting tool first, then use MoodWallet to think about the choices behind the flexible spending. This combination is stronger than asking one app to do everything. The traditional tool supplies the financial facts; MoodWallet helps me interpret the habits that produced them.
The app is especially interesting for people who react badly to shame-based budgeting. A strict limit can be useful, but it can also create an all-or-nothing cycle: I stay within the target for a while, break it once, and then stop tracking altogether. An emotional approach may make it easier to recover from one unplanned purchase because the focus is on learning from the moment rather than declaring the whole plan ruined.
Still, reflection has diminishing returns if nothing changes afterward. I can identify the same emotional trigger repeatedly and remain stuck in the pattern. That is not necessarily a failure of the app, but it is a reason to use its observations as a starting point for a practical adjustment. If stress causes convenience spending, the next step might be preparing an easier meal option, setting a waiting rule for online purchases, or moving a small amount into a separate spending account.
The maintenance burden in ordinary life
The biggest maintenance question is how much attention the app expects from me. Any tool that depends on manual reflection competes with the very moments when I am distracted, rushed, or emotionally tired. If using it requires a long entry after every purchase, I would quickly stop. Its best role is as a lightweight checkpoint attached to meaningful decisions, not as a second job.
I would begin with two or three deliberate check-ins during the week, especially around spending that tends to feel automatic. That is enough to test whether the process is changing my behavior. If I later find the routine easy, I can expand it. Starting small is important because an ambitious tracking plan can create false enthusiasm and then disappear after a busy week.
There is also a maintenance trade-off between honesty and convenience. A quick mood label is easy but may be vague. A thoughtful note is more useful but takes longer. I would avoid writing an explanation for every small purchase and reserve detail for decisions that surprise me, feel emotionally charged, or repeat often. Those entries are more likely to reveal something actionable than a complete diary of minor transactions.
Because the app is currently at version 2.12.0 and supports Android 7.0 or later, it remains accessible to people using older Android devices. That broad compatibility is practical, particularly for anyone who does not replace a phone frequently. I would still keep the app updated when possible, since a habit tool is most useful when it opens reliably at the moment I need it.
The app has a 4.3 average from over one hundred ratings, with more than forty written reviews and over ten thousand installs. Those figures suggest a modest but real user base rather than a finance platform with universal reach. I would read that as a reason to approach it as a focused tool with a particular philosophy, not as a complete standard that should replace every other money app.
Where fatigue can set in
The first source of fatigue is repetition. If every interaction asks me to name the same emotions without helping me see a new pattern, the process can become performative. A good habit should make decisions clearer, not merely add a ritual around them. I would periodically ask whether the app has changed what I do, not just whether I have continued opening it.
The second is emotional overinterpretation. Not every purchase needs a psychological explanation. Sometimes I buy something because it is useful, enjoyable, or convenient. Treating normal spending as evidence of a problem could make the experience unnecessarily heavy. I prefer using the app selectively, especially when a purchase feels automatic, regrettable, unusually large for me, or connected to a recurring mood.
The third is the gap between awareness and control. Recognizing that I spend when stressed does not automatically make stress disappear. If I expect MoodWallet to solve that underlying issue, I will probably be disappointed. Its realistic benefit is helping me notice the link early enough to create a better response. The work of changing the response still belongs to me.
There is a practical limitation for anyone seeking precise financial administration. A mood-centered system cannot, by its nature, answer every question that a ledger answers. It may tell me that a purchase felt rushed, but I still need another way to check whether my monthly obligations are covered. Users who want one dashboard for accounts, bills, savings goals, and detailed categories should choose a broader finance solution instead.
The optional purchase model may also affect how comfortable I feel over time. Since the app is free but offers individual in-app purchases from six dollars and ninety-nine cents up to eighty-nine dollars and ninety-nine cents, I would not assume that every useful element is included at no cost. Before committing to a paid option, I would use the free experience long enough to establish whether the underlying habit works for me. Paying for more material will not compensate for a routine I never maintain.
How it compares with familiar alternatives
Compared with a spreadsheet, MoodWallet is less powerful for calculations but more inviting at the exact point where an emotional purchase happens. A spreadsheet can show totals with great precision, yet it usually will not prompt me to examine why I reached for my card. If my main weakness is organization, the spreadsheet wins. If my main weakness is automatic behavior, MoodWallet has the more relevant angle.
Compared with a conventional budgeting app, it is less about enforcing limits and more about building awareness. Traditional budgets are better when I need a clear spending ceiling, planned allocations, or a view of upcoming obligations. MoodWallet is better when a rigid limit has not addressed the reason I keep exceeding it. The two approaches can work together, but I would not expect either one to replace the other completely.
Compared with a notes app or journal, MoodWallet offers a purpose-built context for money-related reflection. A generic note can be more flexible and may take less effort, but it also requires me to create my own structure. MoodWallet’s advantage is that it keeps the exercise tied to spending behavior. Its disadvantage is that I have less freedom if my personal method does not fit the app’s intended flow.
Compared with simply checking a bank statement, the app adds a layer of interpretation. A statement can reveal what happened; it rarely explains the emotional conditions that made it happen. That extra context is the reason to keep MoodWallet around. If I am already disciplined and only need accurate records, the additional reflection may feel unnecessary.
My long-term verdict on keeping it installed
I would keep MoodWallet installed if I were actively working on impulse spending, stress-related purchases, or an uneasy relationship with strict budgeting. Its lasting value is not in making money management disappear. It is in giving me a manageable pause before I repeat a behavior I already know is unhelpful. That is a narrower promise than full financial control, but it is also more believable.
I would not keep it as my only finance app. For bills, account balances, savings targets, debt planning, and exact monthly totals, I would use a conventional finance tool alongside it. MoodWallet earns its place as the behavioral companion: the part of my system that asks whether a purchase reflects a considered choice or a temporary reaction.
The best test is simple. Use the free version for a meaningful stretch, focus on one spending pattern, and look for a change in decisions rather than a large volume of entries. If the app helps me pause before a recurring impulse, it has earned continued attention. If I only open it because the concept feels interesting, then the novelty has already run its course.
My recommendation is therefore positive but specific. MoodWallet is worth trying for people who want to spend with more awareness and who dislike the pressure of traditional budgeting. It is not the right choice for someone seeking detailed financial administration or automatic control. Its real strength is turning a vague feeling about spending into a moment I can examine and act on. When I use it selectively, connect its insights to practical changes, and accept that it complements rather than replaces ordinary money tools, it has a reasonable chance of becoming a lasting part of a healthier financial routine.
Pros
- Clear overview of income, expenses, and available balance
- Helpful budgeting tools for tracking spending habits
- Simple interface suitable for users new to money management
- Expense categories make recurring spending easier to identify
- Can encourage better financial discipline through regular monitoring
Cons
- Manual transaction entry may become time-consuming
- Some advanced features may require a paid subscription
- Limited usefulness if you need detailed investment tracking
- Financial insights depend on accurate and consistent data entry
- Privacy concerns may matter when storing sensitive money information
FAQs for MoodWallet: Money Management
What is MoodWallet: Money Management, and who is it designed for?
MoodWallet: Money Management is a personal finance app designed to help users monitor spending, organize income and expenses, and build a clearer picture of their financial habits. Its approach may be especially useful for people who want a simple way to record transactions and understand how their mood, routines, or lifestyle choices affect money decisions. It can suit beginners, students, families, and anyone seeking better day-to-day financial awareness.
Does MoodWallet connect directly to my bank accounts?
Whether MoodWallet supports direct bank synchronization depends on the version, region, and services available on your device. Before downloading, check the app’s current store description and permission details to confirm whether transactions must be entered manually or can be imported automatically. If you prefer maximum privacy, manual tracking can be reassuring; however, it may require more consistency than an app with automatic account connections.
Is MoodWallet: Money Management free to use?
MoodWallet may offer a free download with some features available at no cost, while additional tools, advanced insights, or an ad-free experience could require in-app purchases or a subscription. Pricing and included features can change, so review the Google Play Store or Apple App Store listing before installing. Also check whether a free trial automatically becomes a paid subscription and how cancellation works.
Is my financial information safe when using MoodWallet?
You should review MoodWallet’s privacy policy and the permissions requested during setup before entering sensitive financial information. Avoid adding passwords, banking login credentials, card security codes, or other details that the app does not clearly require. If the app supports cloud backup or account synchronization, understand how data is stored, shared, and deleted. Using a device lock and keeping the app updated can provide additional protection.
Can MoodWallet replace a bank, accountant, or professional financial adviser?
No. MoodWallet should be treated as a budgeting and personal organization tool rather than a replacement for your bank, accountant, or qualified financial adviser. It can help you track spending, recognize patterns, and set practical goals, but its calculations depend on the information you provide and may not reflect every financial obligation. For taxes, investments, debt restructuring, or major financial decisions, consult an appropriate professional.

MoodWallet: Money Management
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@allo.finance, visit https://allo.finance, or review their https://allo.finance/privacy.










